The short answer for La Verne renters
Often yes, when the water event is sudden and accidental. A supply line bursts under the kitchen sink, a water heater fails overnight, or a pipe in the wall gives way and soaks your couch, your bed and your electronics. Many renters policies treat that kind of loss to your personal property as a covered event.
The answer changes when the water arrives slowly, comes from outside, or traces back to something you ignored. Policies differ, so nothing here replaces the wording in your own document. Treat this post as a guide to the questions worth asking your insurer, not a ruling on your claim.
What a renters policy is built to protect
A renters policy mostly covers your belongings, your extra living costs if the unit becomes unlivable, and your liability if you damage someone else's property. It generally does not insure the building. The landlord's own insurance deals with the structure.
It usually will not pay to replace saturated drywall or subfloor, because those belong to the building. Ask your insurer how it treats improvements you made yourself.
Covered and not covered: common patterns
These are patterns, not promises. Your exclusions, deductible and limits decide the real outcome.
| Situation | Often treated as covered | Often treated as not covered |
|---|---|---|
| Supply line or pipe bursts suddenly | Damage to your belongings and possibly added living costs | Repair of the pipe or the building itself |
| Water heater or appliance fails and floods the unit | Your wet furniture, clothing and electronics | The appliance, if it is the landlord's |
| Leak from the unit above, sudden and accidental | Your belongings damaged by the water | Building repairs, which fall to the landlord's coverage |
| Slow drip behind a wall for months | Rarely, and only if the policy says so | Long-term leakage and neglect are common exclusions |
| Storm water or groundwater entering at ground level | Usually not under a standard renters policy | Flood damage is usually excluded and needs separate flood coverage |
| Sewer or drain backup | Only if you added a water backup endorsement | Usually excluded without that add-on |
Wording varies between insurers. Ask yours about deductibles, limits on electronics, and whether the policy pays replacement cost or depreciated value.
Landlord duties and tenant duties in general
In general terms, the landlord is responsible for the building, its plumbing and the repair of damage to it. The tenant is responsible for protecting their own property, reporting problems quickly and not making a bad situation worse. Your lease and local tenancy rules fill in the details, so read both.
The practical rule is speed. Tell the landlord or manager in writing the moment you see water. A timestamped text or email beats a phone call nobody remembers.
What usually falls to you
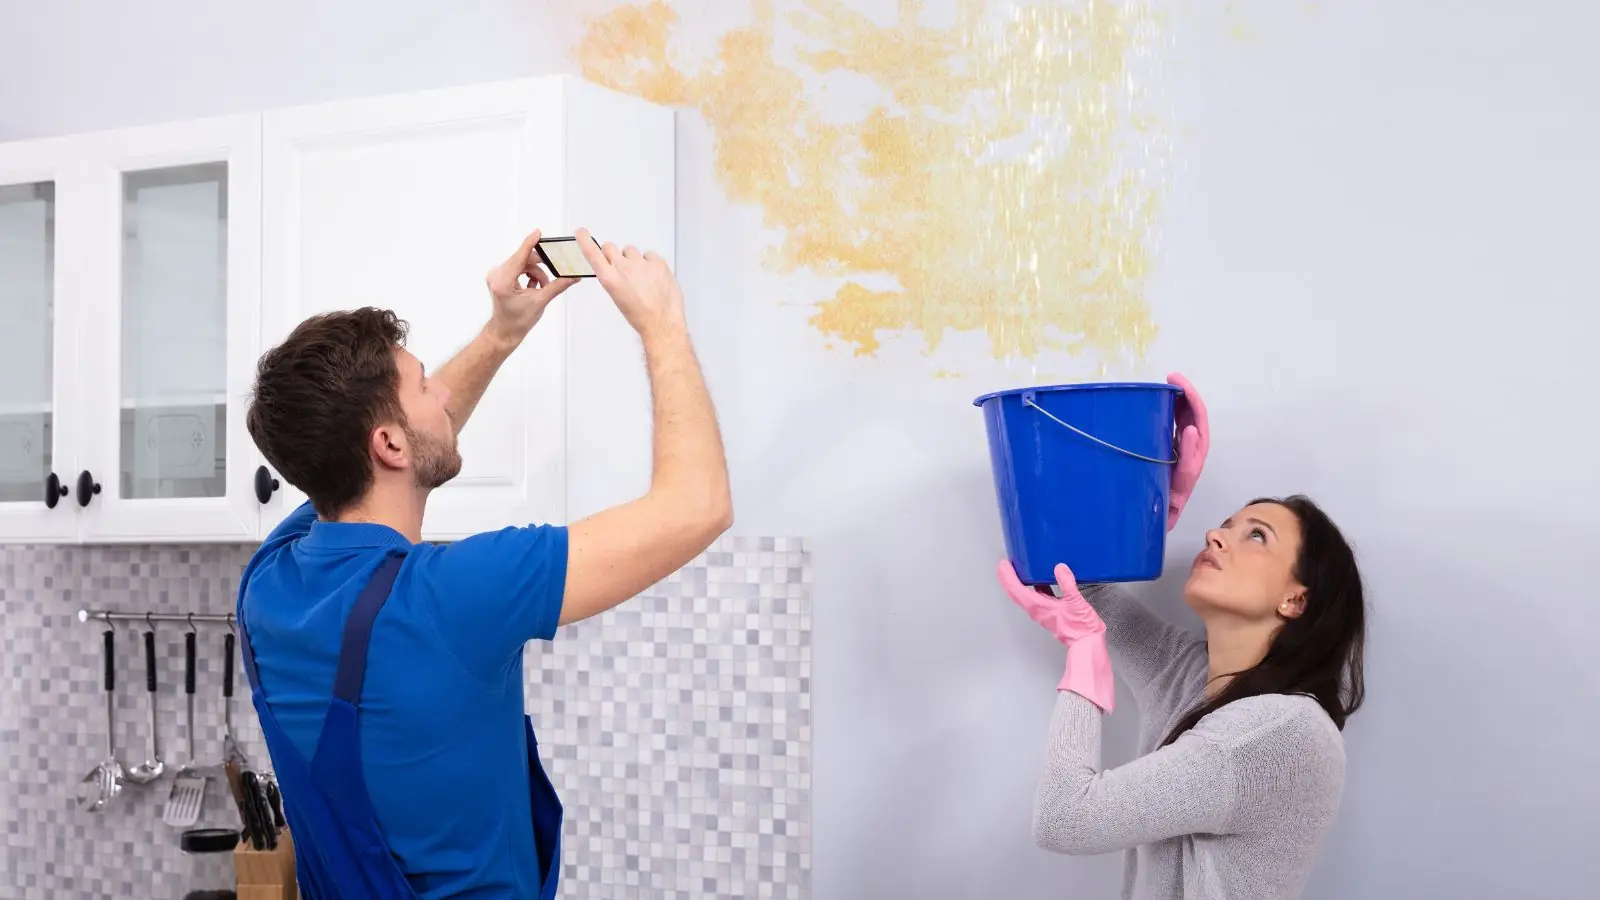
Stop the water if you can safely reach the shutoff, lift belongings off wet floors, and take photos before anything is moved. Report the loss to your insurer promptly and keep receipts. California's Department of Insurance advises taking reasonable steps to protect the property.
What usually falls to the landlord
Fixing the source of the leak, repairing walls, ceilings and flooring, and arranging professional drying of the structure. Rebuilding work such as water damage repair after drying is normally arranged through the property owner.
The first day after water shows up
- 1
Stop the source and make it safe
Close the fixture shutoff or the main valve. Stay away from wet outlets and any water near electrical equipment. If there is an electrical or gas risk, leave and call the utility or 911 first.
- 2
Photograph before you move anything
Shoot wide and close photos of the water, the source and every wet item. Video a slow walk through each room. Do this before you lift or discard things.
- 3
Notify the landlord and your insurer
Send the landlord a written message with photos. Then report the loss to your own insurer promptly and ask what they need from you.
- 4
Start drying without throwing things away
Pull wet furniture off floors, open windows if weather allows and run fans. Do not discard damaged items until the adjuster has had a chance to inspect, unless they are unsafe to keep.
Our 24/7 dispatch line sends a licensed and insured crew to start extraction and drying. Call, and we will explain what the crew does while you contact your landlord and insurer.
What to document for a renters claim
Insurers decide claims on evidence. Build the file while the damage is still visible.
Claim paper trail
- Dated photos and video of the source, the water and every damaged item
- A written list of damaged belongings with brand, age and rough value
- Receipts for emergency purchases and any hotel or storage costs
- A log of every call and message with the landlord and the insurer
- Copies of all written correspondence, including texts and emails
- Written, line-item bids if any repair work is quoted to you
- The date you first noticed the water and the date you reported it
Check your policy before the leak, not after
Pull out your declarations page today. Look for the personal property limit, the deductible, any separate limit for electronics, and whether loss of use is included. Then read the water section for words like sudden, accidental, seepage, continuous and backup, since those decide most disputes.
If you disagree with a denial, California requires it in writing with reasons and a mention of your right to ask the Department of Insurance to review.
Why drying fast helps everyone in the building
Wet drywall and carpet pad break down quickly, and a damp wall can feed mold when it stays wet. Crews use moisture meters and thermal cameras to find hidden water, then air movers and LGR dehumidifiers to dry it. Many structures dry in a few days, depending on materials and conditions.
In multi-unit buildings a leak can reach neighbors through shared walls. Fast emergency water removal limits how far damage spreads. Neighbors in Claremont and San Dimas face the same question, and we send crews to both towns from La Verne.
Renting in La Verne: what the local numbers mean
Census QuickFacts lists La Verne's owner-occupied housing rate at 69.2 percent for 2020 to 2024. That leaves roughly three in ten homes that are not owner-occupied, so many La Verne households deal with a landlord when water appears. Save your landlord's contact details and your lease in your phone today.
The City of La Verne runs the local water utility. Its customer service line is (909) 596-8744, and there is no published water emergency line. If a leak starts, close the shutoff valve for the fixture or the main valve, then call customer service only for supply questions.
The 2025 city water quality report lists groundwater hardness of 351.7 ppm. Hard water leaves mineral scale, so check supply connections under sinks for crusty buildup and photograph it, since it can mark a weeping connection.
Source: U.S. Census Bureau QuickFacts for La Verne city, and the City of La Verne 2025 Water Quality Report.
Renters insurance and water damage questions
It often covers your belongings when a pipe bursts suddenly, but usually not the pipe or the building. Your landlord's policy handles the structure. Check your policy and ask your insurer how your deductible applies.
Some policies include loss of use or additional living expense when a covered loss makes the unit unlivable. It depends on the cause and the limits. Ask your insurer before booking, and keep every receipt.
Sudden and accidental water from a neighbor's unit often counts as a covered cause for your belongings. The building repairs fall to the landlord. Document the source with photos and report it to both your insurer and your landlord.
Flood damage is usually excluded from standard policies and needs separate flood coverage. California's Department of Insurance says the same about standard homeowners policies. Ask your insurer what yours says.
Ask the landlord first, since the structure is theirs. If a delay would let damage spread, tell them in writing what you plan to do. California requires a contractor licence when a job totals 1,000 dollars or more, and you can check any licence on the CSLB website.